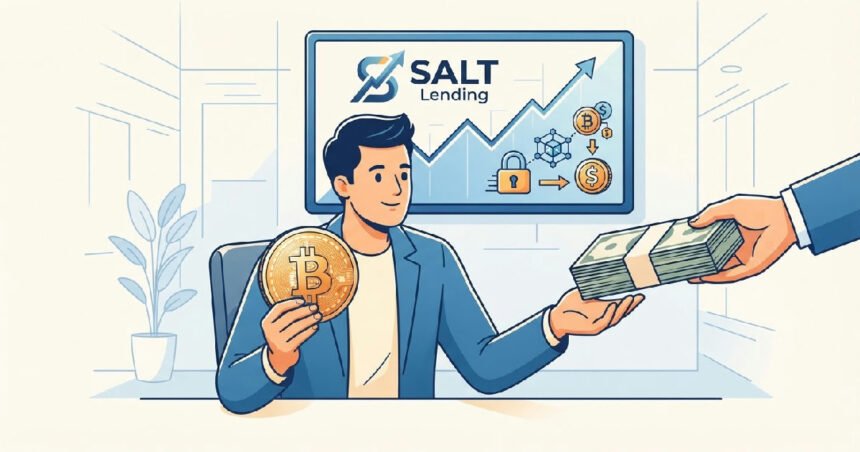
Bitcoin holders are increasingly discovering new ways to leverage their digital assets beyond simply “HODLing,” thanks to the growing utility of digital currencies like Bitcoin. This financial shift allows individuals and businesses to unlock capital without liquidating their cryptocurrency holdings through Bitcoin-backed loans. A recent video from SALT Lending, a pioneer in the space, highlighted how these loans facilitate broader financial goals.
The firm detailed several strategic applications, moving beyond basic cash access to encompass major purchases, business expansion, and investment diversification. This approach offers a significant alternative to the traditional dilemma faced by long-term Bitcoin owners: either selling appreciated assets or leaving their value untapped. The evolution of this market reflects a maturing ecosystem for digital assets.
Understanding Bitcoin-backed loans
For years, long-term Bitcoin investors confronted a binary choice when needing funds: sell their Bitcoin, potentially incurring significant capital gains taxes, or forgo accessing the value locked in their holdings. Bitcoin-backed loans present a third, more flexible option. They allow holders to borrow against their Bitcoin, using it as collateral, while still maintaining exposure to the asset’s potential future appreciation.
This mechanism operates similarly to conventional collateralized lending. Borrowers deposit their Bitcoin with a lender or a designated third-party custodian. In return, they receive a loan, typically in fiat currency or stablecoins, based on a percentage of their Bitcoin’s value. This Loan-to-Value (LTV) ratio determines the amount of capital available, providing immediate liquidity for various financial needs.
Strategic Applications for Bitcoin Holders
SALT Lending’s recent insights underscore diverse applications for this type of financing. One primary use case involves real estate. Bitcoin holders can leverage their crypto assets to secure loans for property purchases, avoiding the need to sell off their Bitcoin in a potentially unfavorable market. This preserves their long-term investment while facilitating a major acquisition.
Business expansion represents another compelling opportunity for entrepreneurs. Owners can use Bitcoin-backed loans to fund operations, hire new employees, or pursue growth initiatives. This strategy eliminates the necessity of selling their Bitcoin or diluting their equity in the business, offering a non-dilutive financing solution. It provides a strategic avenue for growth capital.
Investment diversification also features prominently as a benefit. Loan proceeds enable borrowers to enter other markets or explore new investment opportunities. They gain access to additional asset classes without cashing out their Bitcoin. This allows for a broader portfolio strategy while retaining a core position in their original digital asset.
Navigating Tax Implications and Market Volatility
One of the most attractive aspects of Bitcoin-backed loans for many investors lies in their potential tax efficiency. Selling highly appreciated Bitcoin can trigger capital gains taxes in numerous jurisdictions. Conversely, receiving funds from a properly structured loan generally doesn’t constitute a taxable sale, deferring any tax event. This provides a crucial advantage for wealth management.
However, it’s imperative for individuals to understand that tax circumstances vary widely, requiring personalized advice from qualified professionals. While loans can defer capital gains, they introduce other financial risks. The inherent volatility of Bitcoin, which secures these loans, is a significant factor borrowers must consider.
Understanding Loan-to-Value Ratios and Liquidation Risks
Because Bitcoin is a volatile asset, significant price declines can impact the terms of these loans. A sharp drop in Bitcoin’s value can increase a loan’s Loan-to-Value (LTV) ratio. This might necessitate borrowers providing additional collateral to maintain their loan terms, a process known as a margin call. Failure to do so could trigger the liquidation of their collateral.
Lenders often implement strict protocols to manage this risk, but borrowers must remain vigilant. A clear financial strategy is essential, weighing the benefits of liquidity against the costs of borrowing, repayment obligations, and the ever-present risk of market fluctuations. These loans are a sophisticated financial tool, not a risk-free option.
The Evolution of Bitcoin-Backed Lending
The concept of collateralizing crypto assets for loans isn’t new, but the market has matured significantly. SALT Lending, founded in 2016 in Denver, Colorado, was an early pioneer in this space. Its mission was to allow cryptocurrency holders to obtain cash loans without selling their assets, bridging the gap between digital assets and traditional finance.
Shawn Owen, co-founder and CEO, has been a vocal advocate for Bitcoin’s role as “pristine collateral.”
Early adoption also saw Maker launching in December 2017, offering a widely used crypto-backed loan product by allowing Ethereum to be locked as collateral for DAI. These early ventures laid the groundwork for the more robust ecosystem seen today. The regulatory landscape has also evolved considerably since these initial offerings.
Overcoming Past Challenges and Bolstering Trust
The crypto lending market faced severe challenges in 2022, marked by the bankruptcies of major lenders like Celsius and BlockFi. These failures, which wiped out billions in customer funds, led to increased regulatory scrutiny and a necessary deleveraging of the market. The industry has since focused on prioritizing collateralization and transparency, driving a rebound.
Centralized lending, for instance, has more than tripled from its late-2023 low, indicating renewed confidence and improved operational practices. This recovery is a testament to the underlying demand for these services and the industry’s efforts to build more secure frameworks. Firms offering digital asset custody have become critical players in restoring investor trust.
Institutional involvement has also surged, with major financial institutions launching Bitcoin-backed lending services for select clients in the first half of 2026. This mainstream embrace signals a growing acceptance of Bitcoin as a legitimate financial asset.
Further validating this trend, Ledn completed the first bond in asset-backed securities supported by a portfolio of Bitcoin-backed loans in February 2026, with S&P Global Ratings assigning ratings to the offering. This securitization marks a significant step toward financial integration.
A Maturing Market and Future Outlook for Bitcoin Finance
The Bitcoin-backed loan market is projecting substantial growth, reflecting its increasing relevance in global finance. Projections indicate the broader crypto lending platform market could reach $25.06 billion by 2030, with a Compound Annual Growth Rate (CAGR) of 18.5%. In 2025, the service-side crypto lending market was estimated at approximately $14.8 billion, expanding to around $17.9 billion in 2026. These figures highlight a rapidly expanding sector.
Loan volume across all cryptocurrencies saw a nearly 50% year-over-year increase, reaching $67 billion in Q1 2026, according to Galaxy Research. While the crypto-backed lending market experienced a slight contraction to $67.4 billion in Q1 2026 after peaking in Q3 2025, this was largely characterized as healthy deleveraging rather than a collapse. It signifies a market seeking more sustainable growth.
Innovations and Regulatory Frameworks
Companies like SALT Lending continue to innovate, introducing features such as “Stabilization” and “Shield” tools. These are designed to protect borrowers from sudden price drops by offering an “extension of time” rather than immediate liquidation of collateral. Such advancements mitigate some of the inherent risks associated with volatile assets.
Furthermore, Shawn Owen announced “Salt Switch” in May 2026, a product aimed at beating competitor lending rates, underscoring ongoing competition and product development.
Regulatory bodies are also adapting to this evolving financial landscape. The U.S. Securities and Exchange Commission (SEC) has increased scrutiny, leading to enforcement actions against some crypto lending platforms in the past. However, the focus has shifted towards establishing clearer guidelines.
The New York Department of Financial Services (NYDFS) and Wyoming regulators, for example, have agreed to coordinate on digital asset oversight. This coordination is crucial for fostering a stable and compliant environment for stablecoin liquidity and other crypto-financial products.
As Bitcoin continues its journey from a niche asset to a more integrated financial instrument, lending solutions are set to play an increasingly vital role. They empower holders to use their digital wealth actively without surrendering long-term positions. This strategic approach to liquidity marks a significant step in mainstreaming cryptocurrency into broader economic activities.