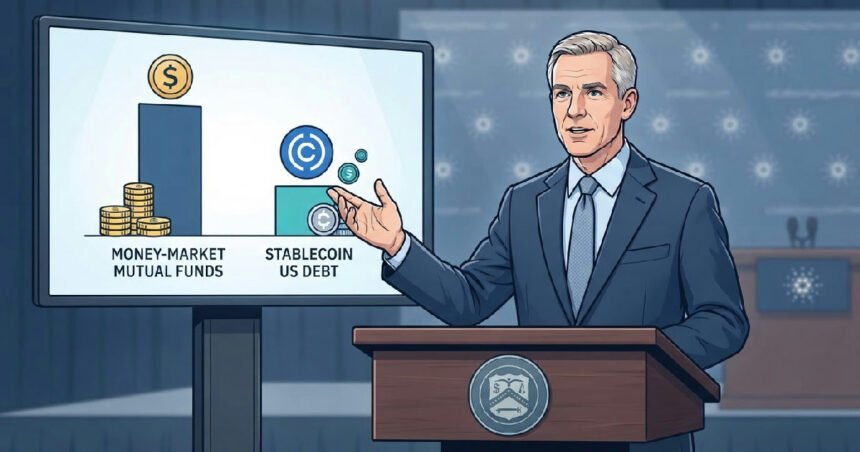
Traditional money-market mutual funds, not the burgeoning crypto sector, were the primary buyers of the US government’s recent debt issuance surge. These established financial players absorbed approximately 85% of the more than $550 billion in new Treasury bills supplied during July and August, according to the Treasury Department. This clarifies the current role of stablecoin US debt in the broader financial landscape.
The clarification, delivered in remarks by Deputy Treasury Secretary Francis Brooke on September 22, provides a crucial dose of reality regarding the current role of stablecoins in government finance.
Understanding stablecoin US debt demand
While stablecoin issuers are significant players, holding nearly $200 billion in short-dated US debt, their status as major holders doesn’t mean they drove the recent buying frenzy. The data paints a more complex picture of where demand truly originated.
The Treasury’s data highlights the critical difference between a “stock” of assets and a “flow” of new investment. The nearly $200 billion figure associated with stablecoin providers represents their total holdings—a substantial stock of Treasury bills and similar near-maturity securities. It’s a snapshot of their accumulated reserves, not a measure of their purchasing activity during a specific window.
In contrast, the 85% figure attributed to money-market funds is a flow measurement. It directly addresses who bought the more than $550 billion in *additional* net bill supply that hit the market in July and August. This indicates that when the government significantly increased its short-term borrowing, traditional cash managers were the ones who stepped up with the marginal capital to meet that new supply.
This distinction is vital for understanding the current market structure. While the crypto industry is a large and growing creditor to the US government, the latest wave of financing was predominantly handled by the old guard of finance.
The Treasury’s breakdown did not specify how the remaining 15% of the new issuance was allocated among other buyer groups, but the dominance of money funds is the clear takeaway from the report.
The hidden overlap between stablecoins and money markets
The line between stablecoin demand and money-market fund demand is not as clear-cut as it might appear. A significant portion of stablecoin reserves is invested through the very money-market funds that the Treasury identified as the primary buyers. This creates an overlap where crypto-driven demand is channeled through traditional financial vehicles, making direct attribution tricky.
Circle, the issuer of the prominent USDC stablecoin, provides a compelling case study. In a second-quarter filing, the company disclosed that as of June 30, approximately 84% of its reserves were held in the Circle Reserve Fund. This fund is structured as a Rule 2a-7 government money-market fund, placing its assets squarely within the category that dominated the summer’s Treasury bill absorption.
Further examination of the fund’s holdings reveals another layer of complexity. An annual shareholder report from April 30 showed its assets included not just $19.1 billion in direct Treasury obligations but also $47.0 billion in repurchase agreements (repos) collateralized by Treasuries.
This means stablecoin reserve exposure to government debt isn’t just about direct ownership; it also comes through other financial instruments, further blurring the lines between buyer categories and highlighting the intricate plumbing connecting crypto to traditional finance.
Federal Reserve and foreign investors add to the mix
Beyond money funds, two other major players have shaped the demand for US debt in 2026: the Federal Reserve and foreign investors. The Fed has been a substantial buyer, purchasing more than $300 billion in Treasury bills through September 22. These are not direct purchases at auction but secondary market operations for reserve management and the reinvestment of principal payments from its other holdings.
These operations are designed to maintain ample reserves in the banking system and manage the composition of the Fed’s balance sheet, known as the System Open Market Account (SOMA).
Data from the central bank shows its holdings of Treasury bills swelled from around $234 billion at the end of 2025 to over $550 billion by mid-September 2026. This demonstrates the Fed’s significant role in providing secondary market demand, which faces its own challenges for the Federal Reserve.
Meanwhile, foreign demand for US bills has shown signs of revival. After consecutive declines in April, May, and June, foreign residents increased their holdings by $38.8 billion in July, according to the Treasury International Capital (TIC) report.
The rebound was led by private foreign buyers, who added $45.0 billion, offsetting a small $6.3 billion decline from official foreign institutions. While this data only covers July, it signals a renewed appetite from overseas after a period of selling.
A future of expanding stablecoin demand
While traditional finance may have absorbed the most recent surge, the Treasury Department clearly views the crypto sector as a key source of future demand for government debt. Deputy Secretary Brooke specifically pointed to the potential for stablecoin providers to continue expanding and increasing their Treasury holdings as the regulatory environment becomes clearer, particularly with the finalization of rules implementing the GENIUS Act.
This forward-looking statement frames stablecoins not just as current holders but as a growth area for Treasury financing. Clearer regulation could unlock more direct and transparent investment from issuers, potentially making them a more dominant force in future debt auctions. The current market shows how growing institutional demand is reshaping financial landscapes, and stablecoins are a part of that evolution.
For now, the story of the summer of 2026’s debt issuance is one of traditional finance stepping up. The data provides a valuable baseline: stablecoins are already material investors in US debt, but their path to becoming the primary absorbers of new supply depends heavily on regulatory developments and the strategic decisions of issuers.
As the views from institutional crypto investors continue to mature, their influence on the largest debt market in the world is only set to grow.